Los Angeles Reverse Mortgage Lending Limit versus Payout
A high home value and a large lending limit can still produce a much smaller cash amount. The missing piece is how the loan is calculated—and what must be paid before money reaches you.
The direct answer: For a Home Equity Conversion Mortgage (HECM), the FHA-insured reverse mortgage, the national lending limit is a ceiling used to determine a valuation base called the maximum claim amount. An FHA factor converts that base into the initial principal limit. Required payoffs, financed costs and applicable reserves then affect usable proceeds, while first-year disbursement rules affect when funds can be accessed. None of those amounts is automatically your cash payout.[7][9]
For a Los Angeles homeowner comparing a HECM with a jumbo reverse mortgage, the useful question is not simply, “Which has the higher maximum?” It is, “How much can I actually use, when can I use it, and what obligations come with that amount?” A jumbo reverse mortgage is a separate proprietary product; its written terms, not the HECM formula, determine the comparison.[7][15]
Key takeaways
- Home value, maximum claim amount, principal limit, available cash and outstanding debt are different numbers.[9]
- Age and the expected interest rate help select the HECM factor; lien payoffs and costs affect what remains afterward.[9]
- The first-year limit includes mandatory obligations, not just money deposited into your account.[9]
- Undrawn credit is not already borrowed money. The balance reflects advances and subsequent accruals and charges.[3][9]
- A home above the HECM cap is a reason to compare offers—not proof that a jumbo reverse mortgage provides more usable cash.[7][9]
Video series · 7 episodes · about 20 minutes
Watch the 7-Part Video Series
Reverse Mortgage Explained: A 7-Part Guide for California Homeowners. George Kfoury walks through the numbers in a reverse mortgage estimate, one short episode at a time. Pick any episode, or press Play all to watch them in order.
-
Episode 1 · 3:09
How Much Can I Get From a Reverse Mortgage? Value vs. Cash | Ep. 1
Learn how home value, the HECM lending limit, borrowing capacity and usable reverse mortgage cash differ. George Kfoury explains the key numbers to check in a California reverse mortgage estimate.
-
Episode 2 · 3:16
Reverse Mortgage Age Rules: Which Spouse's Age Counts? | Ep. 2
See how age, spouse status and interest-rate assumptions affect a reverse mortgage estimate. Learn which age is used in a HECM calculation and why the expected rate can differ from the note rate.
-
Episode 3 · 2:58
Reverse Mortgage Costs: What's Left After Your Mortgage Payoff? | Ep. 3
Understand how an existing mortgage payoff, closing costs, mortgage insurance and applicable set-asides affect reverse mortgage proceeds. Follow an illustrative breakdown from borrowing capacity to available cash.
-
Episode 4 · 2:37
Reverse Mortgage Payout Options: Cash Now or Later? | Ep. 4
Explore reverse mortgage payout options, including cash at closing, later access and payment plans. Learn how first-year disbursement rules and the loan’s rate structure affect when money may be available.
-
Episode 5 · 2:27
Reverse Mortgage Credit Line Growth: What Actually Grows? | Ep. 5
Understand what HECM line-of-credit growth means and how withdrawals affect available credit and loan debt. A hypothetical example explains why credit-line growth represents borrowing capacity rather than savings interest.
-
Episode 6 · 2:58
Do You Still Own Your Home With a Reverse Mortgage? | Ep. 6
Learn about home ownership, repayment triggers, spouse and heir considerations, and ongoing responsibilities with a reverse mortgage. Understand why property taxes, insurance, maintenance and occupancy remain part of the decision.
-
Episode 7 · 2:54
HECM vs. Jumbo Reverse Mortgage: Compare More Than the Maximum | Ep. 7
Compare HECM and private jumbo reverse mortgage options for a higher-value California home. Look beyond advertised maximums to review usable proceeds, timing, costs and household protections using consistent assumptions.
Now playing · Episode 1 of 7 · 3:09
How Much Can I Get From a Reverse Mortgage? Value vs. Cash | Ep. 1
Learn how home value, the HECM lending limit, borrowing capacity and usable reverse mortgage cash differ. George Kfoury explains the key numbers to check in a California reverse mortgage estimate.
An estimate is not approval or a loan offer.
Read the transcript · Episode 1
Episode 1 transcript: How Much Can I Get From a Reverse Mortgage? Value vs. Cash | Ep. 1
In this episode:
- 0:00 Home value versus usable cash
- 0:25 The value used in a HECM calculation
- 0:58 Borrowing capacity comes before cash
- 1:31 Is unused credit already debt?
- 2:05 Four questions to ask about an estimate
- 2:31 Start with your own numbers
Your home is worth a million dollars. What could a reverse mortgage actually put in your hands? Your home value alone can't tell you. Before you can answer, you need to separate four things: the value used in the calculation, your borrowing capacity, the cash you can access and the debt you would owe. Let's put those on screen, so you know which number to look for when you review an estimate.
Let's focus on a HECM, the FHA-insured reverse mortgage. You'll hear that pronounced heck-um. For a HECM on a home you already own, the starting value is generally the lower of the applicable appraised value or the national HECM limit. That starting value is called the maximum claim amount. The national limit is updated by calendar year. It is a ceiling used in the calculation, not a promised payout. A home worth more than that ceiling doesn't automatically create a larger HECM starting value.
Next, that calculation base is multiplied by an FHA factor. The factor depends on the applicable age and expected interest rate. The result is your initial principal limit. Think of it as gross borrowing capacity before money is disbursed. It still isn't your spending cash. Existing eligible mortgage debt, financed closing costs and any required reserves can reduce what remains available. The payment plan and first-year rules then affect when you can receive funds. Each step answers a different question.
if an estimate shows an unused credit line, is that whole amount already debt? No. Your outstanding balance reflects money advanced to you or paid on your behalf, plus interest, mortgage insurance and applicable charges. Undrawn credit is available borrowing capacity under the loan's terms. It isn't cash already in your account. Financed closing costs may create an opening balance before you take spending cash. Watch these two panels: available to borrow and already owed. They answer different questions.
Here's a useful way to read an estimate. What value did the lender use? What gross capacity did that produce? How much can I access now and later? And what would I owe? Imagine an offer that shows a large principal limit but never identifies cash at closing. To see the full picture, ask for a breakdown. Makes it easier to compare offers without guessing.
The point of an estimate is to connect the loan to your actual goal, whether addressing an existing mortgage or planning for future expenses. Your home's value alone can't answer that question. If you'd like to explore what a reverse mortgage can do for you, use the link in the description to visit our reverse mortgage calculator. In one minute you get an instant written breakdown of capacity, costs, cash access, and starting debt. An estimate is free and a starting point, not a loan approval.
Episode 2 transcript: Reverse Mortgage Age Rules: Which Spouse's Age Counts? | Ep. 2
In this episode:
- 0:00 Which age and rate belong in your estimate?
- 0:29 HECM age requirements and spouse status
- 1:04 How age affects borrowing capacity
- 1:32 Expected rate versus note rate
- 2:04 Compare the same starting assumptions
- 2:39 What to ask before requesting an estimate
You're 74, your spouse is 67. Which age belongs in your reverse mortgage estimate? For a HECM, the FHA insured reverse mortgage, the calculation uses the youngest borrower or eligible non-borrowing spouse. That detail can affect the amount. And age is only part of the picture. The rate used to size your loan may have a different job from the rate charged on your balance. Let's separate those inputs before you compare offers. HECM borrowers generally must be at least 62 at closing. Other reverse mortgage programs start at 55 years old. The factor calculation uses the age of the youngest borrower or eligible non-borrowing spouse. Being an eligible non-borrowing spouse is a different role from being a borrower, so don't assume you can leave a younger spouse out of the conversation to obtain a larger number. Ask how that spouse is being classified, whose age is being used, and what protections conditions apply. Those details belong in the written discussion. Age helps select the principal limit factor. With other assumptions held constant, older applicable ages generally support greater initial borrowing capacity. But this is a comparison of different ages under the same assumptions. It's not a promise that waiting for your next birthday will deliver a certain increase. Rates, the property value, and program rules can change. Ask the lender to show the applicable factor, rather than treating age as a fixed percentage of your home's value. Now suppose a lender quotes an interest rate. Here's the question to ask: is that the rate used to size my initial capacity or the rate charged on my balance? For an adjustable rate HECM, the expected rate helps size capacity. The note rate is used to charge interest on outstanding debt under the loan’s terms. They aren't automatically the same. For a fixed rate HECM, They are equal. Now, ask which rate you're seeing and how any future adjustments are limited. Imagine comparing two estimates that use different property values, different spouse assumptions, and different rates. A larger headline amount wouldn't tell you which offer is better. First line up the assumptions. Then compare gross capacity, cash available, costs, and how the balance may change. Paying off a larger existing mortgage reduces what remains afterward. It doesn't change which age belongs in the FHA factor calculation. Keeping those steps separate helps you see why the final cash figures differ. You don't need to memorize the FHA tables to have a useful conversation. Take one question with you. Which person's age and which rate did you use, and can you show me how they affect my estimate? If you'd like to begin with your situation, use the link below to visit our reverse mortgage calculator. Have information about both spouses ready. The next useful step is a clear written explanation of the assumptions, not a guess based on age alone.
Episode 3 transcript: Reverse Mortgage Costs: What's Left After Your Mortgage Payoff? | Ep. 3
In this episode:
- 0:00 Is the headline amount your cash?
- 0:10 Illustration: subtract the mortgage payoff
- 0:44 Mortgage insurance and closing costs
- 1:17 Financed fees versus out-of-pocket costs
- 1:45 What set-asides are for
- 2:24 The breakdown to request for your estimate
You see $200,000 on a reverse mortgage estimate, and you wonder, is that how much I get? Before you make plans for it, let's see where that money goes. Say that $200,000 is your borrowing capacity. We'll use made-up numbers to keep this simple. You still owe $120,000 on your mortgage, so that much goes toward paying it off. Now we're down to $80,000 before the other items. Next, let's allow $15,000 for costs added to the loan and $5,000 set aside for a specific purpose. That leaves $60,000. But hold on, we haven't checked when you can actually receive it. So don't read that as $60,000 in your bank account at closing. Now you may be wondering what's in those costs. With a HECM, the upfront mortgage insurance is 2% of the maximum claim amount. That's the calculation base. There's also annual mortgage insurance: half a percent of the outstanding loan balance charged over time. So those two percentages are based on different amounts. You may also see an origination fee, an appraisal, and title charges. The HECM origination fee can't be more than six thousand dollars, but that doesn't cap your entire closing bill. Now, if someone says you don't need to bring cash for a fee, ask how it's being paid. The fee may still be there, just added to the loan. When you finance a fee, it uses loan proceeds and increases what you owe. If you pay it out of pocket, you're using your own money instead. Either way, let's get every cost spelled out. And look beyond closing day, because interest and other charges continue over time. You may also see money set-aside for repairs, servicing, or property charges. Think of it as money earmarked for a particular job. It isn't extra spending money. A life expectancy set aside or LESA can reserve funds for certain taxes and insurance. The lender's review of your finances helps determine whether you need one. Setting that money aside doesn't automatically mean all of it is already debt. You still have responsibilities, including taxes, insurance, and keeping the home in good condition. A set-aside doesn't necessarily cover every property expense. So let's ask for four things on that estimate. The payoff, the costs, the set-asides, and what you can actually access. Then ask what becomes debt now and what might be advanced later. To start with your own numbers, use the calculator button below this video. Have your approximate home value and mortgage balance ready. Then get a written breakdown so you can decide whether it fits your needs.
Episode 4 transcript: Reverse Mortgage Payout Options: Cash Now or Later? | Ep. 4
In this episode:
- 0:00 Why the timing of cash matters
- 0:27 First-year access: an illustration
- 1:05 Why the first-year result can differ
- 1:18 Lump sum, credit line or monthly payments
- 1:55 Later access and the questions to ask
- 2:21 Explore the amounts and timing for your plans
What if you need money for a home repair now, but want a cushion for later? With a reverse mortgage when you get the money matters just as much as how much you can borrow. For a HECM, the FHA-insured reverse mortgage, there are limits on what can be paid out during the first 12 months. That includes required payments like paying off your old mortgage. So the first-year limit isn't all cash for you to spend. Let's use an adjustable-rate HECM and some made-up numbers. Say the starting borrowing capacity, called the principal limit, is $150,000. For this example, use 60% as the first-year limit. We'll assume no set-asides reduce it. That gives us $90,000 for the first year. Now suppose $60,000 goes to the mortgage payoff and other required costs. That leaves up to $30,000 for you during those first 12 months. That's why I'd ask to see the amount you could actually receive after the required payments. Some cases allow a higher first-year limit and set-asides can change the result. Have the lender show your numbers. And remember, we're talking about the whole first year, not just closing day. Let's say you only need part of the money now. You'd like the rest available if something comes up. That's where your payment plan matters. With a fixed-rate HECM, you receive your cash in one lump sum. There isn't a credit line to draw from later. An adjustable-rate HECM can offer a credit line, monthly payments, or a combination. With a credit line, you can request money when you need it, within what's available and the loan's terms. Monthly payments can run for a period you choose. A tenure plan offers ongoing monthly payments, as long as the loan stays in place and you meet its conditions. And you don't automatically get another check when the first year ends. What you can draw later depends on your plan and the loan's terms. That's why I'd start with your plans. What do you need at closing? What might you need during the first year? And what would you rather keep available for later? Ask for those amounts separately when you review an estimate. Then you can see whether the payment plan fits what you actually want to do. If you'd like to start with your own numbers, use the calculator button below this video. Then we can look at how much you may be able to receive and when.
Episode 5 transcript: Reverse Mortgage Credit Line Growth: What Actually Grows? | Ep. 5
In this episode:
- 0:00 What credit-line growth really means
- 0:27 A hypothetical five-year growth illustration
- 0:57 Available credit is not deposited cash
- 1:08 What changes when you draw $40,000
- 1:30 Interest applies to the outstanding balance
- 1:55 Conditions for continued access
- 2:10 Compare flexibility with the loan costs
What if your reverse mortgage credit line gets bigger while you leave it alone? That can happen with an adjustable-rate HECM, the FHA-insured reverse mortgage. It means you may have more room to borrow later. It doesn't mean the bank paid you interest. Think of two separate numbers: what you can borrow and what you already owe. Credit line growth can increase the borrowing room. Taking money out adds to what you owe. For this made-up example, we're past the first year and $100,000 is available as unused credit. We'll assume 6% interest plus half a percent in annual mortgage insurance. That's a 6.5% annual growth rate, calculated monthly. If those rates stayed the same, with no withdrawals, new fees, or new set-asides, you'd have about $138,000 available five years later. Actual rates can change, so this is an illustration, not a forecast. That bigger number is credit you could borrow. It's not money deposited into your account. Continued access depends on keeping the loan in place and meeting its conditions. Now suppose at that five-year point you decide to take $40,000 out. Using our rounded figures, the available credit drops from about a hundred thirty eight thousand to about ninety eight thousand. The forty thousand you take becomes an advance added to your loan balance. The unused part can keep growing under the loan's rules. You aren't charged interest on credit you haven't drawn. Interest and mortgage insurance apply to the outstanding loan balance. And you may already owe money for a mortgage payoff or financed closing costs, even before taking cash for yourself. So a higher interest rate isn't simply good news because it makes the credit line grow faster. It can also increase the interest cost on what you owe. You still need to live in the home as required, pay property taxes and insurance, and keep it maintained. When you get an illustration, ask to see available credit and projected debt separately. Have the lender show the rate assumptions too. If you'd like to start with your situation, use the calculator button below this video. Then we can look at whether that future flexibility fits your plans and the loan's costs.
Episode 6 transcript: Do You Still Own Your Home With a Reverse Mortgage? | Ep. 6
In this episode:
- 0:00 Ownership and a HECM mortgage lien
- 0:28 Taxes, insurance, maintenance and occupancy
- 1:00 When repayment can become due
- 1:24 Borrower and non-borrowing spouse roles
- 1:54 Heirs and HECM non-recourse protection
- 2:15 Moving plans, alternatives and counseling
- 2:37 Match an estimate to your household plans
Does getting a reverse mortgage mean you're giving up your home? With a HECM, the FHA-insured reverse mortgage, you still own it. The lender has a lien on the property, just as it would with another mortgage. While you meet the loan's conditions, you generally don't have to make monthly principal and interest payments. That can help your monthly budget. Interest and other loan charges still add to what you owe. Here's what I wouldn't want you to overlook. Look, the property taxes and homeowners insurance still need to be paid. HOA dues and other property charges may apply too. You still take care of the home too, including the everyday repairs that come up. And it needs to remain your principal residence. So when we look at an estimate, I'd also ask whether those ongoing expenses fit your budget. Falling behind on the requirements can make the loan due and could lead to foreclosure. What if your plans change? If you sell, the loan generally needs to be repaid. Repayment also generally becomes due when the last borrower permanently moves out or passes away. Spouse protections can change how that works. A long stay in a care facility can matter too. Ask how the occupancy rules would apply to your household before you need that answer. What about your spouse? Their role on the loan matters. If you're both borrowers, a surviving borrower can generally stay and continue receiving loan payments while meeting the requirements. A spouse who isn't a borrower has different protections. An eligible non-borrowing spouse may be able to postpone repayment if the conditions are met. But that doesn't give them access to new loan advances. Have the lender confirm your spouse's status in writing. And if your children hope to keep the house, talk about repayment now. They may need their own financing when the loan becomes due. There's also a protection called non-recourse. With a HECM, the lender can't pursue other assets to cover a shortfall. But the family still has to settle the loan to keep the house. I'd also want to know how long you expect to stay. If a move is coming soon, upfront costs may make another option a better fit. Downsizing, other financing, or waiting may be worth comparing. HECM borrowers must meet with a HUD-approved reverse mortgage counselor. Bring your family questions and someone you trust if you'd like. Want to see what this could look like for you? Use the calculator button below. Then we can look at the estimate alongside your household budget and family plans. You can explore the numbers before deciding whether to move forward.
Episode 7 transcript: HECM vs. Jumbo Reverse Mortgage: Compare More Than the Maximum | Ep. 7
In this episode:
- 0:00 Is the bigger headline the better offer?
- 0:16 HECM and private jumbo options
- 0:54 Align the starting assumptions
- 1:20 Mortgage payoff, loan costs and reserves
- 1:36 Cash at closing, year one and later
- 1:47 Debt, repayment and household protections
- 2:06 What to have ready for an estimate
Say you're looking at two reverse mortgage estimates. One shows a bigger number at the top. Would you pick that one? I'd want to know what that number actually gives you. How much could you use? When could you use it? And what would you owe? For a higher-value Los Angeles home, that conversation may include both a HECM and a jumbo reverse mortgage. A HECM is the FHA-insured program. It has HUD rules for things like borrowing limits, mortgage insurance, and payment options. A jumbo is a private reverse mortgage. It may offer more borrowing capacity on a higher-value home, but the terms depend on the particular product. So I'd ask to see its rates, costs, draw options, and spouse protections in writing. A jumbo isn't FHA insured, and we shouldn't assume it works just like a HECM. Before comparing the offers, start with the same home value and borrower details, so we're looking at the same situation. Check the ages used, how your spouse is treated, and the date of each estimate. Ask whether the rates are fixed or adjustable, and how they could change. If the assumptions differ, have the lender explain why. Otherwise, a bigger number could simply come from a different starting point. Now, put that headline number aside for a minute. Ask what has to go toward your current mortgage, what the loan costs, and whether money is being reserved. Have the lender separate costs added to the loan from anything you'd pay out of pocket. Then ask what you could actually receive at closing, during year one, and later. Somebody who needs a larger amount now may want something different from someone keeping a cushion for later. I'd also compare how the debt could grow, what makes repayment due, and what happens to a spouse or heirs. And ask what happens if the home eventually sells for less than the debt. Have the lender explain the non-recourse protection in that specific loan. You don't need a perfect file to start asking questions. Have an approximate home value, your current mortgage balance, your ages, and your spouse's information handy. Tell me what you'd like the money to do for you and when you'd need it. If leaving the home to family matters, let's include that in the conversation. Use the calculator button below to explore your own numbers. It's a starting estimate, not an approval or a substitute for appraisal and underwriting. Then we can look at the available options and ask for written breakdown. You don't have to make the decision from one big number. Let's look at what the offer would actually mean for you.
Educational only — not financial, legal or tax advice. Examples are illustrative. Reverse Mortgage California · Company NMLS #2530594 · George Kfoury NMLS #365129 · Equal Housing Opportunity.
Which reverse mortgage limit are you looking at?
Start by asking the lender to label each number. A discussion about “how much you qualify for” is incomplete unless it distinguishes lending capacity from cash and debt.
| Term | What it means | What it does not mean |
|---|---|---|
| National HECM mortgage limit | A limit FHA publishes for each calendar year, used in calculating the maximum claim amount.[9] | A promised borrower payout. |
| Maximum claim amount, or MCA | The lesser of the applicable appraisal and national limit; HECM for Purchase also includes the sales contract price in the lesser-of calculation.[9] | Your initial borrowing capacity or opening debt. |
| Initial principal limit, or PL | MCA multiplied by the applicable FHA principal limit factor, before disbursements.[9] | Unrestricted spending cash. |
| Net available capacity | Capacity remaining after relevant payments and reserves. HUD’s net principal limit also subtracts initial disbursements, including borrower cash, so the measurement point matters.[9] | A permanently fixed cash entitlement. |
| First-year gross disbursement limit | The limit on disbursements during the first 12-month period, including mandatory obligations and borrower cash.[9] | A cash-only allowance. |
| Outstanding balance | Funds advanced to you or on your behalf, plus accrued interest, mortgage insurance and applicable charges.[3][9] | Your home’s value or an undrawn credit line. |
For a nonpurchase HECM, the starting formulas are:
MCA = lesser of the applicable appraised value or applicable national HECM limit.
Initial principal limit = MCA × applicable FHA principal limit factor.[9]
If the appraisal is already above the national cap, increasing it further does not, by itself, enlarge the MCA. That is why a higher-value property does not necessarily produce a higher HECM principal limit.[9]
The appraisal rules matter, too. When HUD’s collateral risk assessment requires a second appraisal, the lower appraisal is used. Closing costs are not added to the appraised value, and initial mortgage insurance is not deducted to calculate the MCA. The sales contract price is an additional input only for HECM for Purchase—not an extra valuation test to import into a nonpurchase transaction.[9]
Whose age and which interest rate affect the principal limit?
The principal limit factor, or PLF, is an FHA-supplied multiplier. The lender must select the appropriate HUD table entry using the age of the youngest borrower or eligible non-borrowing spouse and the expected interest rate.[9]
HECM borrowers must be at least 62 at closing. An eligible non-borrowing spouse has a different role: that spouse’s age can affect factor selection without making the spouse a borrower.[17][9]
HUD’s age rule rounds up when the next birthday is less than 183 days after closing. A separate calculation involving an ineligible non-borrowing spouse is required for disclosure; it is not the factor used to size the actual proceeds.[9]
This creates an important comparison discipline:
- Different applicable age: Ask the lender to identify the correct HUD factor.
- Different expected rate: Ask for the corresponding factor and revised principal limit.
- Different mortgage payoff: Keep the principal-limit calculation separate; the payoff changes the funds remaining afterward.[9]
Do not assume waiting for a birthday produces a particular dollar increase. A meaningful comparison requires the actual factor and otherwise consistent assumptions.
How does the principal limit change by age at a 6.00% expected rate?
Hold the expected rate at 6.00% and compare a $500,000 appraised property in a nonpurchase HECM. This expected rate is an illustrative comparison assumption, not a current market quote. The maximum claim amount (MCA) is $500,000 because the appraisal is below the verified 2026 national HECM limit of $1,249,125.[9][43]
Gross initial principal limit = MCA × official FHA principal limit factor. This measures borrowing capacity before disbursements, not cash paid to the borrower.[9]
The factors below come from HUD’s official workbook, which the current HUD lender-resource index identifies for cases assigned on or after October 2, 2017.[41][42]
Here, age means the factor age of the youngest borrower or eligible non-borrowing spouse, applying the age-selection rule discussed above.[9]
This table isolates age and gross principal limit rather than calculating net proceeds.
| Age used for the factor | Official FHA factor | Principal limit on a $500,000 property |
|---|---|---|
| 62 | 0.357 | $178,500 |
| 65 | 0.378 | $189,000 |
| 70 | 0.415 | $207,500 |
| 75 | 0.443 | $221,500 |
| 80 | 0.488 | $244,000 |
| 85 | 0.549 | $274,500 |
| 90 | 0.618 | $309,000 |
Official factor entries: HUD principal limit factor workbook.[42]
For example, at age 70, $500,000 × 0.415 = $207,500 in gross principal limit.
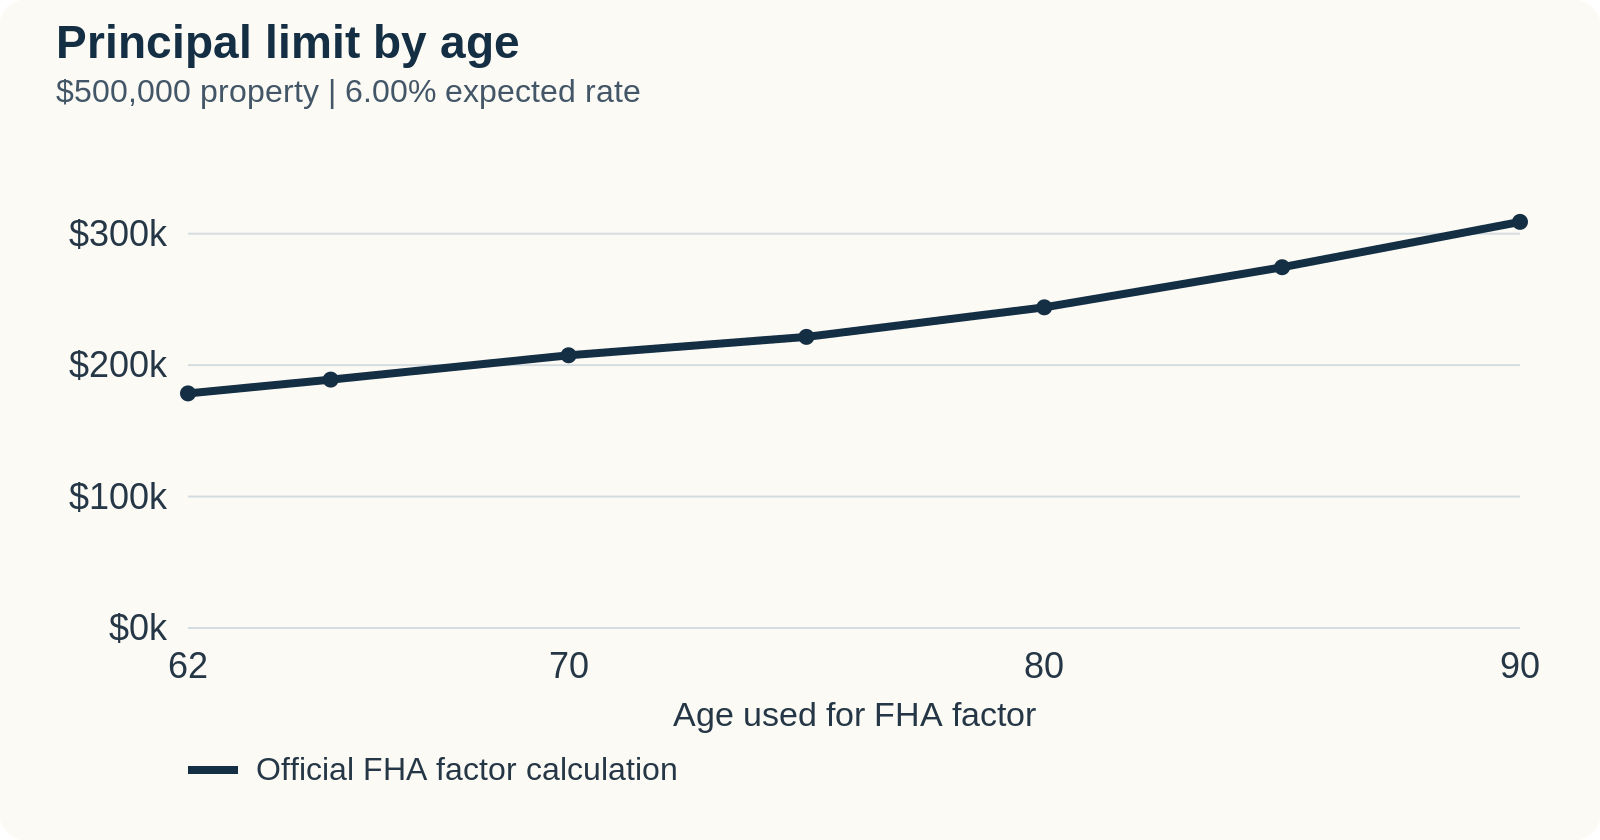
Illustrative cross-sectional comparison: $500,000 appraisal and MCA, nonpurchase HECM, and the same 6.00% expected rate—not a market quote. Official FHA factors determine gross principal limits, not net cash proceeds.[9][42][43]
These rows compare different factor ages under the same stated assumptions. They are not a promise that waiting will produce these dollar amounts: a later application may involve a different expected rate, property valuation, applicable limit or program rules.
Is the expected rate the interest rate charged on the balance?
For a fixed-rate HECM, the expected rate equals the note rate. For an adjustable-rate HECM, the expected rate is the lender’s margin plus the weekly average yield on the 10-year Constant Maturity Treasury index.[9]
The expected rate sizes the principal limit. It is not automatically the initial adjustable note rate used to accrue interest. Ask an adjustable-rate lender to show both rates, identify their purposes and explain the note-rate adjustment terms.[9]
What reduces the money available for spending?
A principal limit is calculated before disbursements. Several uses of the loan can stand between that gross capacity and cash you can spend.
Existing eligible liens. Paying an existing mortgage uses proceeds for your benefit, but it does not put new spending money in your account. Lien eligibility and seasoning requirements can matter, so do not assume every existing debt can be financed.[9]
Mortgage insurance and closing costs. HECM initial mortgage insurance premium, or IMIP, is 2% of the MCA. Annual mortgage insurance is 0.50% of the outstanding mortgage balance, payable monthly. These charges have different bases: neither should be casually applied to the home’s full appraisal or the principal limit.[9]
The origination fee is subject to HUD’s formula and a $6,000 maximum; lenders may charge less. That maximum is not a cap on all closing costs. Appraisal, title, recording and other allowable charges need to be considered separately.[9]
Financing a cost does not waive it. A financed cost uses available proceeds and adds to the amount borrowed.[9]
Applicable set-asides. Repair, servicing-fee or property-charge reserves may reduce available capacity. A Life Expectancy Set-Aside, or LESA, reserves funds for specified property taxes and insurance rather than unrestricted spending. Financial assessment determines whether one is required and whether it is fully or partially funded.[9]
Not every borrower needs a LESA, and a LESA is not a guarantee that every property expense will be covered for life. Taxes, insurance, maintenance, occupancy and other loan obligations remain important. A HECM is debt with repayment triggers, not free money; failure to satisfy obligations can make the loan due and payable.[3][9]
Why can first-year cash be smaller than total capacity?
The first-year rule limits gross disbursements, including required payments. It does not promise every borrower 60% of the principal limit as spending cash.[9]
HUD’s initial disbursement limit is the lesser of:
- The greater of 60% of the principal limit or mandatory obligations plus an eligible additional amount up to 10% of the principal limit; and
- The principal limit minus LESA funds designated for beyond the first 12-month period and the servicing-fee set-aside.[9]
Eligibility for the additional amount applies when mandatory obligations exceed 50% of the principal limit. The borrower must make the required election concerning the additional amount; that election cannot be increased or decreased after closing.[9]
The restriction concerns the first 12-month disbursement period, not just closing day. Later access still depends on the payment plan and loan terms. Unused capacity is not an automatic anniversary check.[9]
How does the payment plan affect later access?
A fixed-rate HECM provides a single lump-sum advance, with no later borrower draws except permitted disbursements from set-asides established at closing.[9]
Adjustable-rate HECMs offer line-of-credit, term, tenure and modified combination plans. Payment-plan changes depend on funds being available. Tenure payments are subject to loan conditions; they are not an unconditional lifetime annuity.[9]
How can an unused HECM credit line expand future borrowing capacity?
An unused adjustable-rate HECM credit line can expand future borrowing capacity, giving a homeowner more available credit to draw later while the loan remains in force and its conditions are met. HUD’s model loan agreement, Section 2.6.1, ties credit-line growth to growth in the principal limit.[37]
This growth is not savings interest, investment income, an advance already received or debt forgiveness.
HUD specifies monthly principal-limit growth at (note rate + annual mortgage insurance rate) ÷ 12.[9]
Unused credit can therefore grow, while a withdrawal reduces available credit. Amounts drawn become debt; interest and mortgage-insurance charges accrue on outstanding advances, not on the undrawn credit itself. Previously financed costs may already be part of the outstanding debt even if the borrower has not taken a cash withdrawal.[3][9][37]
Assumptions for this separate credit-line illustration
This example starts at Year 0 with $100,000 already available as unused credit, after first-year restrictions and with all existing deductions reflected. It is independent of the age table: it does not show that the $500,000 property produces a $100,000 opening credit line.
Assume:
- A 6.00% note rate plus 0.50% annual MIP, producing 6.50% nominal annual credit-line growth, compounded monthly under HUD’s growth rule.[9][37]
- No new fees, reserves or advances, except a $40,000 withdrawal at the end of Year 5, after month 60 growth, in the alternate scenario.
- Constant rates solely for teaching. Actual adjustable note rates—and therefore credit-line growth rates—can change.
The expected rate used to select an initial age factor and the note rate used in the growth calculation are distinct concepts, even though both examples assume 6.00%.[9]
With those constant inputs, the no-withdrawal formula is:
C_y = 100000*(1+0.065/12)^(12y)
Here, C_y is available unused credit after y years. In the alternate scenario, subtract $40,000 after month 60 growth, then apply the same monthly growth assumption to the remaining unused credit. The amounts below are rounded to the nearest dollar.
| Year from illustration start | Available credit: no withdrawals | Available credit: $40,000 withdrawn at end of Year 5 |
|---|---|---|
| 0 | $100,000 | $100,000 |
| 1 | $106,697 | $106,697 |
| 2 | $113,843 | $113,843 |
| 3 | $121,467 | $121,467 |
| 4 | $129,602 | $129,602 |
| 5 | $138,282 | $98,282 |
| 6 | $147,543 | $104,864 |
| 7 | $157,424 | $111,887 |
| 8 | $167,967 | $119,380 |
| 9 | $179,216 | $127,375 |
| 10 | $191,218 | $135,906 |
| 15 | $264,420 | $187,933 |
| 20 | $365,645 | $259,877 |
The no-withdrawal column leaves all unused credit available to grow. The alternate column follows the same path until the end-of-Year-5 withdrawal, then shows growth on the smaller remaining line. At Year 10, available credit is $191,218 without withdrawals, compared with $135,906 after the specified withdrawal. These are available-credit amounts, not outstanding loan balances or investment returns.
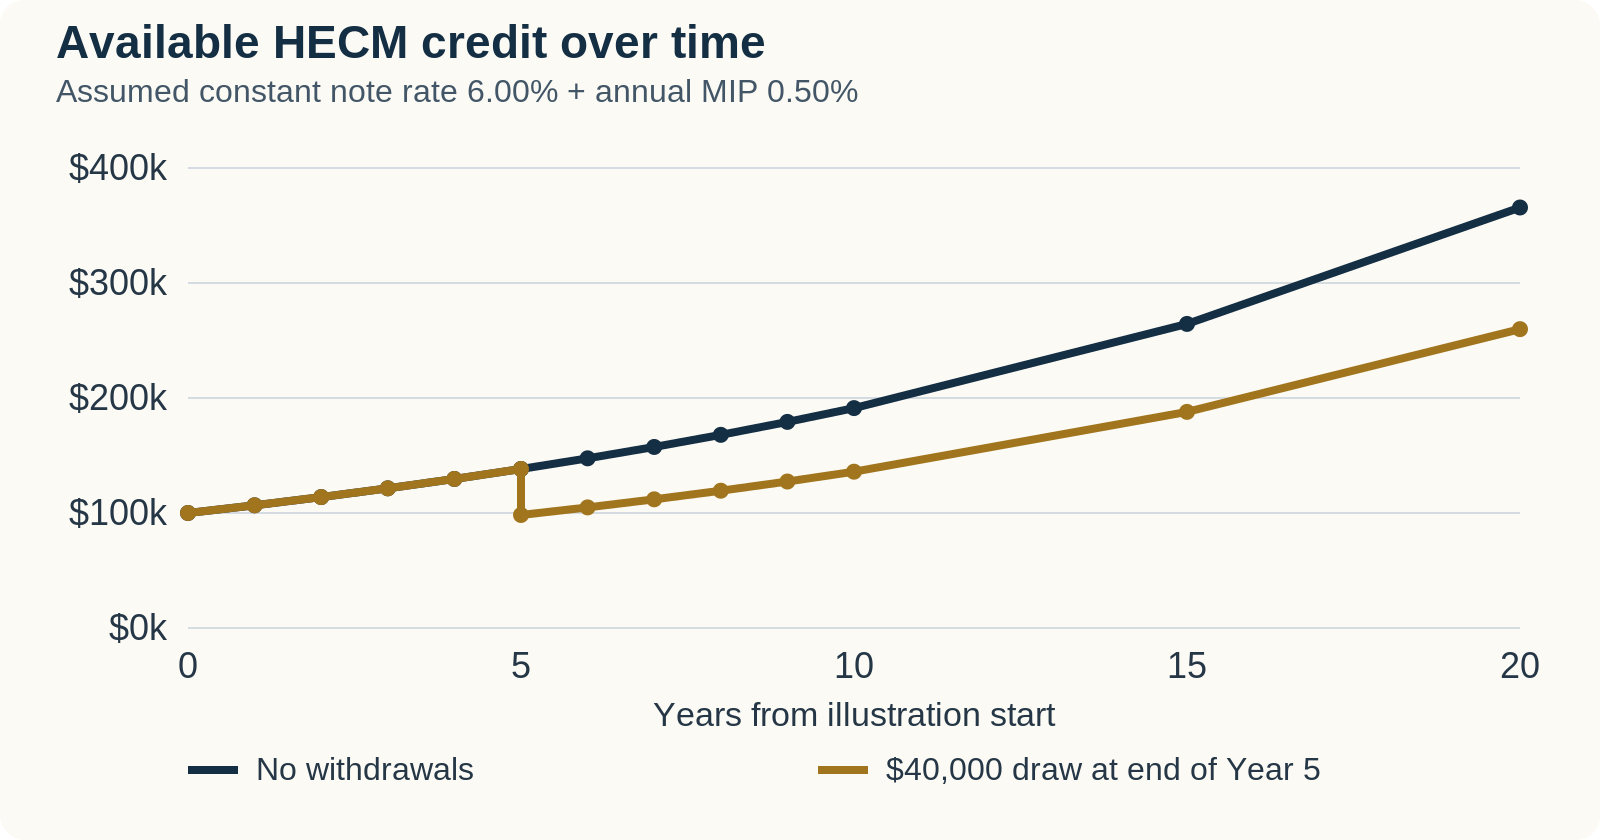
Separate illustration starting with $100,000 already available after first-year restrictions and existing deductions. Both paths assume a constant 6.00% note rate plus 0.50% annual MIP, compounded monthly; the alternate path subtracts $40,000 after month 60 growth. No other new fees, reserves or advances are assumed. Values are rounded to the nearest dollar and are not forecasts.[9][37]
Credit-line growth follows the loan’s principal-limit growth mechanism; it does not receive an annual bonus from recalculating FHA factors as the borrower gets older.[9][37]
Continued access requires the loan to remain in force and obligations—including applicable occupancy, property taxes, insurance and maintenance—to be met. This illustration does not promise fixed future values or unconditional lifetime access.[3][37]
How should Los Angeles homeowners compare a HECM with a jumbo reverse mortgage?
A property above the HECM cap makes a side-by-side evaluation worth considering. It does not establish that a jumbo reverse mortgage will pay more, cost less or better match your plans.
HECMs use HUD’s framework. Jumbo reverse mortgages are proprietary products, and lender-specific underwriting and contracts matter. There is no universal factor table to apply across all jumbo reverse mortgage products.[7][9][15]
| Comparison question | HECM | Jumbo reverse mortgage |
|---|---|---|
| What sets gross capacity? | MCA multiplied by the appropriate FHA factor.[9] | Obtain the specific lender’s written underwriting and proceeds calculation.[7] |
| What does a headline maximum tell me? | The national cap is an input, not cash proceeds.[9] | An advertised product maximum does not establish your net proceeds; availability may be qualified.[7] |
| When can I receive funds? | Rate type, payment plan and first-year rules govern access.[9] | Request the actual draw plans and timing; do not import HECM rules.[7][15] |
| Which insurance and fees apply? | Initial and annual FHA mortgage insurance, plus applicable loan costs.[9] | Compare the product’s own insurance and fee terms rather than assuming uniform treatment. |
| What repayment protections apply? | HECM nonrecourse rules prohibit personal liability for the outstanding balance and a borrower deficiency judgment after foreclosure.[3] | Review the contract’s repayment, spouse and nonrecourse provisions; proprietary protections can differ.[15] |
A product’s advertised maximum is not a check payable to you. The comparison should follow the money through required payoffs, costs, reserves and access restrictions.
What should a useful written comparison include?
Ask each offer to show:
- The property value accepted and the applicable HECM limit year, where relevant.
- Borrower ages and spouse treatment used in the calculation.
- Rate type, expected rate where applicable, note rate and adjustment terms.
- Gross lending capacity and required lien payoff.
- Itemized costs, distinguishing financed charges from cash-paid charges.
- Reserves or set-asides and their intended uses.
- Cash available immediately, first-year access and later draw options.
- Repayment triggers, ongoing obligations and relevant spouse protections.
Keep assumptions identical where possible and label differences where they cannot be held constant. A larger upfront advance and a larger later-access credit option serve different needs; a useful comparison makes that trade-off visible.
Frequently asked questions
Does the reverse mortgage lending limit equal my loan amount?
No. The national HECM limit helps determine the MCA. The initial principal limit then uses an FHA factor, and the outstanding debt reflects advances and subsequent accruals and charges. Those are separate amounts.[3][9]
Does all of my home’s appraised value count?
For a nonpurchase HECM, the MCA cannot exceed the applicable national limit. Value above that cap does not increase the calculation base. For HECM for Purchase, the sales contract price is also part of the lesser-of test.[9]
Whose age matters if my spouse is younger?
The factor uses the youngest borrower or eligible non-borrowing spouse. An eligible non-borrowing spouse’s role in this calculation is distinct from borrower status. Borrowers must be at least 62 at closing.[9][17]
Is the expected rate the rate charged on my balance?
For a fixed-rate HECM, it equals the note rate. For an adjustable-rate HECM, the expected rate is a separate sizing input and is not automatically the initial note rate. Have the lender identify both.[9]
Why does paying off my mortgage reduce the cash I receive?
The payoff uses loan proceeds to discharge eligible existing debt. That is a use of borrowing capacity on your behalf, not additional spending cash. Financed costs and applicable reserves can also reduce what remains available.[9]
Is 60% always the first-year limit?
No. HUD’s formula considers mandatory obligations, eligibility for an additional amount up to 10% of the principal limit, and specified set-asides. The result is a gross disbursement limit that includes required payments, not a cash-only percentage.[9]
Does a higher-value home automatically favor a jumbo reverse mortgage?
No. Compare actual net proceeds, timing, costs, rates and contractual protections. A proprietary product’s advertised maximum does not determine the amount a particular homeowner can receive.[7][15]
Can I take more money later with a fixed-rate HECM?
A fixed-rate HECM is limited to a single lump-sum advance, apart from permitted set-aside disbursements. If later borrower draws matter, compare available adjustable-rate HECM plans and the written terms of any jumbo reverse mortgage alternative.[9][7]
What is the next step toward a usable estimate?
Start with your spending goal, existing mortgage payoff and need for immediate versus later access—not the largest headline number. A useful estimate should distinguish gross capacity, required uses, accessible cash and opening debt.
To understand those numbers for your situation, learn about reverse mortgages or request an estimate at Reverse Mortgage California. An estimate is not approval.
Reverse Mortgage California · Company NMLS#2530594
This article is educational and is not legal or tax advice.
Sources
- [3] 24 CFR 206.27: mortgage conditions and non-recourse protection
- [7] far_wholesale
- [9] HUD Single Family Housing Policy Handbook 4000.1
- [15] Finance of America: heirs and reverse mortgage debt
- [17] cfr_20633
- [37] HUD model adjustable-rate HECM loan agreement
- [41] HUD: current HECM lender resources and factor-table applicability
- [42] HUD official principal limit factor workbook linked for cases on or after October 2, 2017
- [43] HUD Mortgagee Letter 2025-22: 2026 HECM limits